Weekly market update: AI valleys and peaks and Fedspeak dominate the week.
The market and economy
- U.S. stocks gained ground for the week ending November 13, weathering significant volatility. A strong early-week rally in artificial intelligence (AI)-related companies offset a subsequent downturn amid worries regarding allegations that Jensen Huang, the CEO of U.S. based Nvidia Corp., the world’s largest semiconductor company by market capitalization, had a relationship with a businesswoman whom U.S. intelligence reportedly suspected of gathering information for China, prompting national-security concerns. Huang resigned as Nvidia CEO on Thursday. Additionally, hawkish monetary policy comments from two Federal Reserve (Fed) officials rekindled concerns that sticky inflation will lead the central bank to raise interest rates at its meeting on December 8-9.
- During a speech at the Bank of England Watchers Conference in London on Tuesday, Fed Governor Christopher Waller said that inflation remains well above the central bank’s 2% target and expressed his support for a 25-basis-point (0.25%) rate hike in December. He also commented that a 50-basis-point increase should be considered if inflation proves substantially stronger than expected. In prepared remarks at the 11th joint energy conference hosted by the Federal Reserve banks of Dallas and Kansas City on Tuesday, Dallas Fed President Lorie Logan called for at least two additional 25-basis-point rate hikes and commented that the central bank may need to tighten monetary policy more rapidly this winter to prevent elevated inflation from becoming entrenched.
- At the end of the week, CME’s FedWatch Tool, which provides a gauge of the market’s expectations of potential changes to the federal funds target rate while assessing potential Fed monetary policy actions at Federal Open Market Committee meetings, implied a 90.0% chance that the central bank will raise the federal funds rate by 25 basis points to a range of 4.00% to 4.25% at its December meeting.
- There was notable economic news this week. According to the Department of Labor, the consumer-price index (CPI) advanced 0.4% in October, down from the 0.6% upturn in September but slightly above expectations. Fuel oil and gasoline prices rose 2.0% and 1.0%, respectively, in October. Prices for food at home (groceries) increased 0.4% for the month, a notable upturn from the 0.1% dip in September. Utility gas service costs declined 0.8% for the month. Core inflation, as measured by the CPI for all items less food and energy, was up 0.3% in October, matching the increase in September. Costs for transportation services and medical care commodities (prescription drugs, over-the-counter medications, and medical equipment) rose 0.8% and 0.5%, respectively, in October. Conversely, prices for used cars and trucks fell 1.2% during the month. The Department of Labor did not provide year-over-year CPI data as there was no report issued during the 43-day federal government shutdown between October 1 and November 12, 2025.
- The Department of Labor also reported that U.S. inflation at the wholesale level, as measured by the producer-price index (PPI), rose 0.3% in October, down sharply from the 1.4% increase in September. (The PPI tracks the average change over time in selling prices received by domestic producers of goods and service providers.) The goods index advanced 0.5% in October, attributable mainly to a 1.3% rise in food prices. The services index edged up 0.2% due primarily to a 2.0% upturn in costs for transportation and warehousing. Core wholesale inflation, as measured by the index for final demand less foods, energy, and trade services, rose 0.5% in October. The index gained 4.9% for the previous 12-month period.
- According to the National Association of Realtors (NAR), sales of existing homes tumbled 5.5% in October to a seasonally adjusted annual rate of 3.75 million―the lowest level since 2010―and were down 8.8% year-over-year. (Home sales are viewed as an indicator of housing market trends and, by extension, the health of the broader economy.) The median existing-home sale price increased 0.4% over the previous 12-month period to $416,700. The inventory of unsold existing homes as of the end of October stood at 1.59 million—up 1.3% from the end of September—equivalent to a 5.1-month supply at the current monthly sales pace. The NAR considers a six-month supply of homes to be a “balanced market,” in which prices rise modestly. Inventories of greater than six months typically have favored buyers, while a supply of homes that will be depleted in less than six months denotes a “seller’s market.”
Stocks
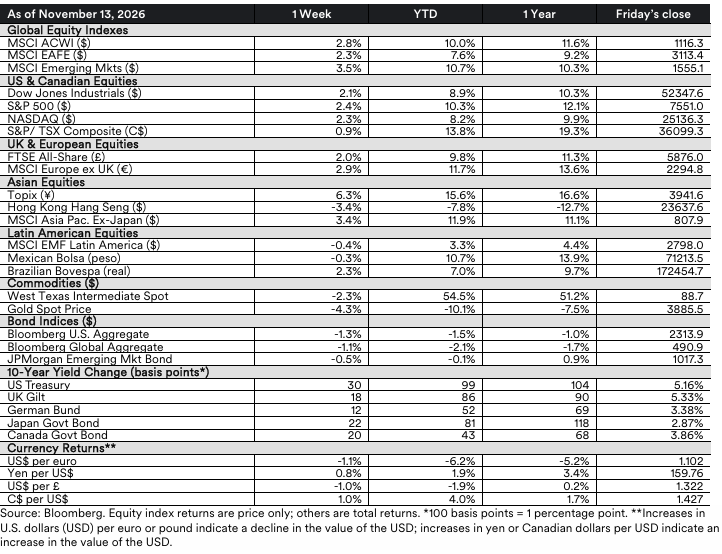
- Global equities posted gains for the week. Emerging markets outperformed developed markets.
- U.S. stocks recorded positive returns during the week. Energy and industrials were the top-performing sectors within the broad-market S&P 500 Index, while materials and real estate were the primary market laggards.
- Growth stocks outperformed value stocks, while large caps topped small caps.
Bonds
- The U.S. bond market finished in negative territory for the week.
- The 10-year U.S. Treasury note yield rose to 5.16% during the week.
- High-yield bonds led the market, followed by investment-grade corporate bonds and government bonds.
IMPORTANT INFORMATION
Index returns are for illustrative purposes only and do not represent actual investment performance. Index performance returns do not reflect any management fees, transaction costs, or expenses. Indexes are unmanaged, and one cannot invest directly in an index. Past performance does not guarantee future results.
This material is provided by SEI Investments Management Corporation (SIMC) for educational purposes only and is not meant to be investment advice. The reader should consult with his/her financial advisor for more information. This material represents an assessment of the market environment at a specific point in time and is not intended to be a forecast of future events or a guarantee of future results. There are risks involved with investing, including possible loss of principal. SIMC is a wholly owned subsidiary of SEI Investments Company.
The information contained herein is for general and educational information purposes only and is not intended to constitute legal, tax, accounting, securities, research or investment advice regarding the strategies or any security in particular, nor an opinion regarding the appropriateness of any investment. This information should not be construed as a recommendation to purchase or sell a security, derivative or futures contract. You should not act or rely on the information contained herein without obtaining specific legal, tax, accounting, and investment advice from an investment professional. Information in the U.S. is provided by SEI Investments Management Corporation (SIMC), a wholly owned subsidiary of SEI Investments Company (SEI).


